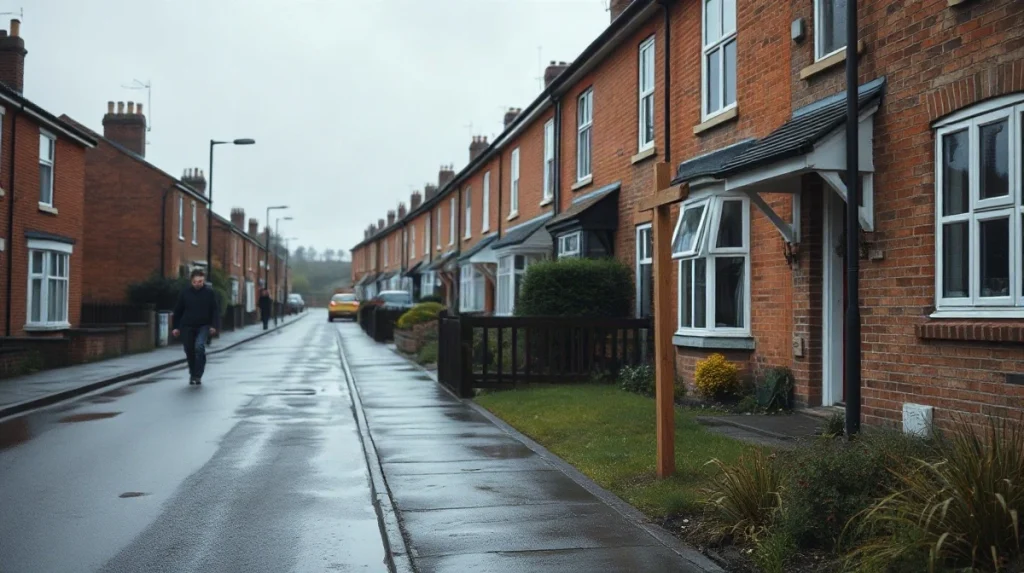
UK five-year fixed mortgage rate hits 6% for first time in three years
The average five-year fixed-rate mortgage in the UK has reached 6.00%, the first time it has crossed that level in three years, according to figures from the financial information provider Moneyfacts cited by Theguardian.
· 3 min read
In this article4 sections
The average five-year fixed-rate mortgage in the UK has reached 6.00%, the first time it has crossed that level in three years, according to figures from the financial information provider Moneyfacts cited by Theguardian. The same data put the average two-year fixed rate at 5.98%, the highest it has been since December 2023.
The last time the five-year average stood at this level was September 2023. The Guardian, which published the figures on Wednesday 7 October 2026, reported that jitters in the money markets have made the loans more expensive for lenders to offer, and the rise now sits between borrowers’ existing plans and their finances.
Also read: Most Americans Still Trust Financial Advisors Over AI Tools for Major Money Decisions, Study Finds
Key facts
- The average five-year fixed-rate mortgage has reached 6.00%, its highest since September 2023.
- The average two-year fixed rate is 5.98%, its highest since December 2023.
- The figures come from the financial information provider Moneyfacts.
- Money-market jitters have raised the cost for lenders of offering these loans.
What the 6% mark means for borrowers
The change matters most to buyers comparing fixed deals, to households whose current fix is about to expire, and to anyone who had budgeted on the assumption that rates would keep easing. A headline average of 6.00% on five-year money is not the rate any individual will be offered: lenders price by deposit size, term, fees and borrower circumstances, so the number is a benchmark rather than a quote.
For readers the practical effect is on affordability rather than the headline alone. A borrower moving onto a higher fixed rate faces a larger monthly payment, which in turn shapes how much a lender will advance and which properties remain within reach. The Guardian’s callout asks readers how the rise affects their finances and whether it changes plans to buy a house or move, and it accepts responses anonymously, with the form encrypted and accessible only to the Guardian. The published piece does not give a single example of an affected household.
Also read: OpenAI fires three safety researchers over data shared with outside AI group
Why it matters
Mortgage costs feed quickly into the wider economy. Higher fixed rates reduce what buyers can borrow, which tends to cool transaction volumes before it shows up in asking prices, and they tie up more of household income that would otherwise be spent elsewhere. The comparison that matters here is with the recent past: both headline averages had been below these levels, and the five-year average has not been at 6.00% since September 2023 or the two-year average at 5.98% since December 2023.
The driver reported is not a change in policy but pricing in the money markets, which determines how much lenders pay to fund fixed-rate loans. That is a market cost, passed through to borrowers.
What to watch
The next signal to watch is whether these averages hold at or above 6.00% or slip back, since the level is set by lenders’ funding costs rather than by any single announced decision. Readers considering a purchase or a remortgage face the practical question of whether to fix now or wait for the market to settle.

Source: The Guardian
Benjamin Carter covers business, finance, and the stock market for StockPil, focusing on the trends and data that matter to everyday investors.
More from Benjamin →